
Tax Planning Advice Sydney — Tax Efficiency Built Into Every Financial Decision
Many Sydney professionals manage their financial planning and their tax position as separate conversations — one with their accountant at year end, the other with a financial adviser when something changes. The result is that financial decisions are often made without a clear picture of how they affect the overall tax position, and tax advice is given without a full view of the financial strategy those decisions are part of.
Nicholas Wong is one of the few financial planners in Sydney who holds a Master of Taxation from the University of Sydney Faculty of Law alongside his financial planning qualifications. That background is not incidental. It means the tax implications of every financial planning recommendation are considered as part of the advice, not added in afterwards.
Japhia Wealth Advisory is an authorised representative of Madison Financial Group Pty Ltd (AFSL No. 246679). Phone: +61 2 7202 8382.
Where Tax Efficiency Matters in a Financial Plan
The financial planning decisions with the most significant tax implications tend to cluster in a handful of areas. These are the areas where a financial adviser who understands tax can make a material difference to the after-tax outcome.
Superannuation Contribution Strategy
How you contribute to superannuation has a direct effect on your tax position. Concessional contributions — salary sacrifice and personal deductible contributions — attract a lower tax rate within the fund than the marginal tax rate most professionals pay on their income. At a high income level, the difference is substantial. The right contribution strategy depends on your income, your existing contribution history, how close you are to annual caps, and how super fits within your broader financial position. We assess this as part of your overall financial plan rather than as an isolated contribution question.
Investment Structure and Ownership
How investments are held affects both the income tax on returns and the capital gains tax treatment when assets are sold. Whether assets are held in your own name, jointly, within superannuation or through another structure is a decision with long-term financial and tax consequences. We consider ownership structure as part of building an investment strategy, with a clear view of how each option interacts with your tax position.
Salary Sacrifice
For professionals on a strong income, salary sacrifice into superannuation can redirect income that would otherwise attract the highest marginal tax rate into an environment where it is taxed at a significantly lower rate. Whether this makes sense depends on cash flow, contribution cap headroom, and the broader financial plan. The right level of salary sacrifice is not the maximum possible — it is the amount that fits the overall strategy.
Transition to Retirement
For professionals in the years approaching retirement, the way income is drawn and how investments are structured can have a meaningful effect on the overall tax position. Transition to retirement strategies, when they are appropriate, combine super access with continued salary sacrifice to improve the after-tax income position while still working. These decisions sit at the intersection of superannuation, income tax and financial planning, and are best considered with an adviser who is familiar with all three.
Working Alongside Your Accountant
Tax return preparation and compliance is your accountant's role. What we do is different and complementary. We consider how your financial decisions affect your tax position and structure recommendations accordingly. Where a financial planning decision has tax implications that your accountant needs to be aware of, we document those clearly. For clients who want us to liaise with their accountant directly on a specific matter, we do that as part of the engagement.
The clients who tend to make the best-connected financial decisions are those who work with both an accountant and a financial planner — and where both advisers are aware of what the other is recommending.
Who This Is Relevant For
Professionals who earn well and have accumulated assets over time are most likely to benefit from financial planning that takes a serious view of tax efficiency. The decisions about how super is contributed to, how investments are structured outside super, and how income will be drawn in retirement all carry meaningful tax implications. Getting those decisions right — before they are locked in — is significantly easier than restructuring afterwards.
If you have not reviewed how your financial strategy and your tax position fit together, or if you have grown your financial position over time without ever connecting the two into a coherent approach, that is worth examining before the decisions that currently look optional become fixed.
Adviser Profile
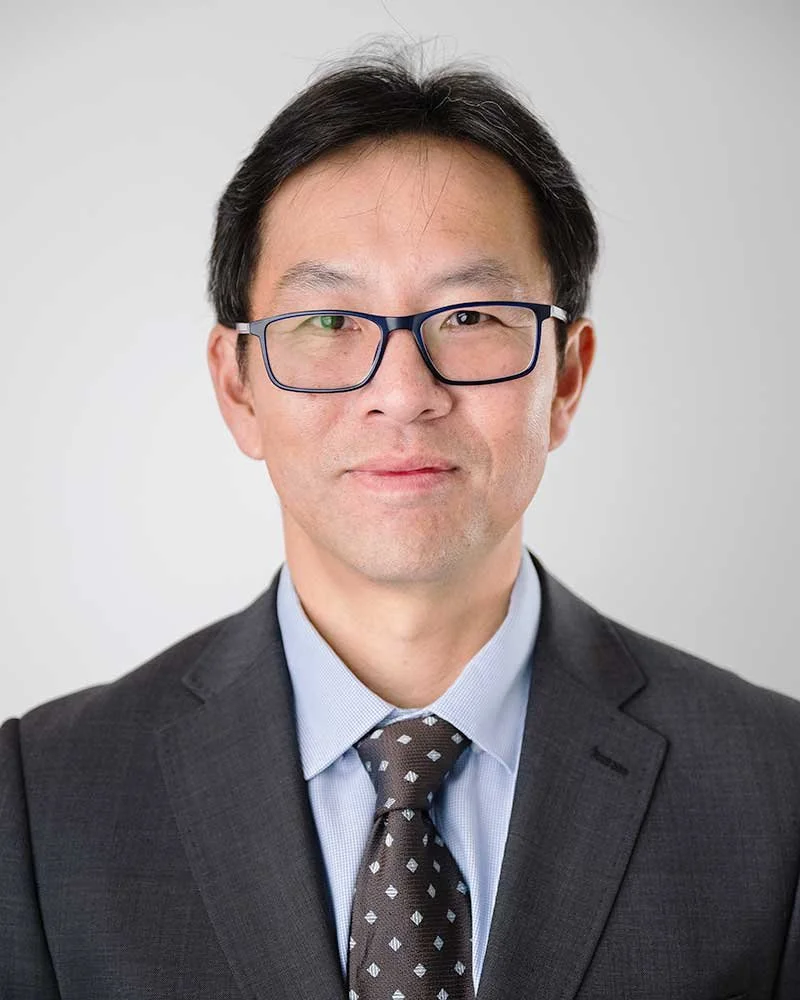
Meet Nicholas Wong — Financial Planner, North Sydney
Nicholas Wong has spent more than 25 years working across finance, tax and financial planning. He advises professionals and established families across Sydney and the Lower North Shore on investment strategy, superannuation, retirement planning and personal insurance, with the tax implications of each recommendation considered as a matter of course.
Nicholas holds a Master of Taxation from the University of Sydney Faculty of Law alongside his financial planning qualifications. That combination is uncommon in financial planning and means clients receive advice that has been thought through across both dimensions from the outset.
He is an authorised representative of Madison Financial Group Pty Ltd (AFSL No. 246679) and is based at Level 24, 100 Miller Street, North Sydney.
Academic Qualifications:
Bachelor of Economics (University of Sydney)
Master of Applied Finance and Investments (FINSIA)
Master of Taxation (University of Sydney Faculty of Law)
Master of Financial Planning (Kaplan Professional)
Professional Qualifications:
Member of Chartered Accountants Australia and New Zealand
Member of the Chartered Institute of Securities and Investment (CISI)
Qualified Tax Relevant Provider as registered by Australian Securities and Investments Commission (ASIC)
What People Say About Japhia Wealth Advisory
-
No. Japhia Wealth Advisory is not a tax agent. Tax efficiency is a consideration within the financial planning advice we provide — not a separate service. If you need tax return preparation or compliance advice, your accountant is the right person. If you want financial planning advice that takes a serious view of how decisions affect your tax position, that is what we do.
-
Nicholas holds a Master of Taxation from the University of Sydney Faculty of Law and is a Qualified Tax Relevant Provider registered with ASIC. His tax background informs how every financial planning engagement is approached, but it does not extend to standalone tax compliance work.
-
Well. We work alongside your accountant rather than in competition with them. Where our recommendations have tax implications, we document those clearly so your accountant has what they need. For clients who want us to coordinate directly with their accountant on a specific matter, we do that as part of the engagement.
-
Tax efficiency within financial planning is most meaningful for professionals earning well and with assets accumulated over time. At lower income levels, the decisions are simpler and the tax implications less significant. At the income levels most of our clients are at — $200,000 and above — the difference between a well-structured financial position and a default one is measurable.

Book a Discovery Session
A discovery session is a 30-minute conversation to discuss your current financial position and what you are looking to achieve. No advice is given in this session. Paperwork is completed beforehand so the time is spent on the conversation.
GENERAL ADVICE WARNING: This information is of a general nature only and neither represents nor is intended to be specific advice on any particular matter. Madison Financial Group Pty Ltd strongly suggests that no person should act specifically on the basis of the information contained herein but should seek appropriate professional advice based upon their own personal circumstances.