
One-Off Financial Advice — Expert Financial Advice for a Specific Decision
Japhia provides one-off financial advice to individuals, families and business owners who have a specific financial question or decision and want professional, documented advice without an ongoing commitment. We are an authorised representative of Madison Financial Group (AFSL No. 246679), holding an Australian Financial Services Licence authorisation and regulated by ASIC.
Not every financial decision requires an ongoing financial planning relationship. Some are specific enough that a single, well-structured engagement with a qualified financial adviser is exactly what is needed: a thorough assessment of your current position relative to the question at hand, a documented recommendation, and the information required to implement or act on that advice. One-off financial advice is a legitimate, properly structured engagement under Australian financial services law, and it is one of the most underutilised options available to Australians who have a specific financial question and are not sure how to get it answered properly.
Japhia provides one-off advice as a formal engagement with a statement of advice, not as a general information conversation. Every one-off financial advice engagement involves an assessment of your personal circumstances, a documented recommendation tailored to your situation, and clear disclosure of fees and any conflicts of interest upfront. You are not paying for access to general financial information. You are paying for personal advice.
What One-Off Financial Advice Is
One-off advice is a single, bounded engagement where a financial adviser assesses a specific aspect of your financial situation and provides a statement of advice covering that area. It does not commit you to an ongoing relationship or any further fees beyond the agreed scope of work. Once the advice has been delivered and you have chosen whether to implement it, the formal engagement is complete.
Under Australian financial services law, one-off advice is still personal financial advice. That means the adviser must understand your personal financial circumstances before making any recommendation, and the advice must be appropriate for your situation and needs. A one-off advice engagement is not the same as speaking to a financial counsellor or reading an article on the Moneysmart website. Those provide general financial information. One-off financial advice produces a documented recommendation specific to your circumstances.
One-off advice is also distinct from general advice. General advice does not take your personal circumstances into account and cannot tell you what is right for your situation. One-off personal financial advice does. Choosing between these types of advice matters because the decision most people face is not a generic one. It is a decision specific to their income, their assets, their existing financial products and their goals.
When One-Off Advice Is the Right Choice
One-off advice suits a specific set of circumstances. Understanding which circumstances those are helps you decide whether a single engagement is appropriate or whether the question is likely to reveal enough complexity to warrant an ongoing relationship.
It suits you well if you have one clear question and the financial position relevant to answering it is relatively contained. A superannuation review for a client who wants to know whether their fund and investment option are appropriate. A retirement income assessment for a pre-retiree who wants to understand what their financial position looks like when they stop working. An insurance review for someone who has not looked at their coverage since their circumstances changed. A second opinion on advice already received from another financial adviser. Each of these is specific enough to be addressed in a single, well-scoped engagement.
It suits you less well if the financial question reveals a position that is more complex than it initially appeared, or if the question is really the entry point to a broader financial plan that needs to be built from scratch. In those cases, the honest answer after a one-off engagement is that more comprehensive advice would serve you better. Japhia will tell you that directly rather than billing for additional work that is not within the original scope. For a broader view of how financial planning needs change across different life stages, our article on the life cycle of financial planning is a useful reference.
For clients facing a specific decision around where to direct surplus funds, our article on loan repayment or additional super addresses a question that one-off advice regularly covers.
What Can Be Addressed in a Single Engagement
Superannuation Review
A superannuation review covers the current fund, investment option, fees and contribution strategy against your stage of life, income and retirement timeline. Many Australians have never looked at their superannuation beyond the statement that arrives once a year, and a one-off review typically identifies at least one area where the position could be materially improved.
The review produces a documented recommendation on what to change and why, with the expected impact on the super balance and the retirement outcome made explicit. It is one of the highest-value uses of a single financial advice engagement because superannuation decisions compound over time, and a poor default that is never reviewed compounds consistently in the wrong direction.
Retirement Income Assessment
A retirement income assessment models what your retirement income looks like from the current financial position. It covers superannuation drawdown, investment income, Age Pension eligibility and the interaction between each of these under current Centrelink rules. The output is a clear picture of what retirement income looks like at your intended retirement age, what the gap is between that income and your target, and what decisions available now would close that gap. For detail on how retirement planning works as an ongoing engagement, see our retirement planning page.
Insurance Review
An insurance review assesses existing income protection, life insurance, trauma cover and total and permanent disability coverage against your actual financial obligations. Most people who have never had their insurance independently reviewed are either underinsured relative to current obligations or paying premiums for cover that is no longer structured appropriately for their situation.
The review produces a documented assessment of what coverage exists, whether it is adequate, whether the structure inside or outside superannuation is appropriate, and what changes would improve the position. For details on insurance advice as a service, see our insurance advice page.
Investment Strategy Review
An investment strategy review assesses an existing portfolio for allocation appropriateness, fee levels, tax efficiency and whether the strategy reflects the client's risk tolerance and investment time horizon. Many investors accumulate holdings over time without a documented strategy connecting them, and the review clarifies what is working, what is not, and what changes would improve the overall position.
The review produces a documented recommendation rather than verbal guidance. Implementing the advice is the client's decision. The fee for advice does not include any implementation work unless that is specifically agreed as part of the scope.
Second Opinion on Existing Advice
A second opinion engagement reviews a statement of advice already received from another financial adviser. It assesses whether the recommendations are appropriate to the client's circumstances, whether the fee structure disclosed is consistent with the advice provided, and whether any conflicts of interest appear to have influenced the recommendations.
This is one of the most consistently valuable uses of one-off advice for clients who have received a recommendation they are uncertain about. A qualified financial adviser reviewing the advice independently, with no financial relationship to the original adviser or to any products recommended, provides an objective assessment that helps the client make an informed decision about whether to proceed.

How to Get the Most Out of One-Off Advice
The most common reason a one-off financial advice engagement underdelivers is insufficient preparation. Coming to the meeting with a specific question rather than a general concern, and bringing the relevant documents, allows the financial adviser to assess the actual position rather than working from estimates.
For a superannuation review, bring the most recent statement from each fund you hold. For a retirement income assessment, bring a summary of all assets, superannuation balances and any existing investment income. For an insurance review, bring the current policy documents or a recent summary from your insurer or superannuation fund. For a second opinion, bring the full statement of advice you have received.
Be specific about the question. One-off advice is most valuable when the question is defined enough that the engagement can produce a clear, documented answer. If the question is too broad, the financial adviser will clarify the scope at the initial meeting before any fees are agreed.
Use the statement of advice (SOA) as a document you act on rather than one you file. The SOA documents what was recommended and why. It is the formal record of the advice and should be revisited as you implement the recommendations.
Who We Help
One-off financial advice suits a specific type of client. You have a question you need properly answered. You want a documented recommendation from a qualified independent financial adviser. You are not ready for, or do not need, an ongoing financial planning relationship at this point.
Professionals who want to know whether their superannuation and insurance are set up correctly without committing to a comprehensive financial plan. Pre-retirees who want a retirement income assessment before deciding when to stop working. Clients who have received advice elsewhere and want an independent second opinion before implementing a major financial decision. Business owners who need advice on a specific financial decision related to their personal position. Anyone who has a specific question that is worth a professionally documented answer.
If you are based in or near North Sydney, a financial planner in North Sydney can provide one-off financial advice in person or via video call. If you are on the Northern Beaches, a financial adviser on the Northern Beaches can do the same.
How We Work
Understand
We start with the free initial consultation, approximately 30 minutes, to understand your specific question and the financial position relevant to answering it. We clarify the scope and agree on the fee before any further work begins.
Analyse
We review the relevant documents and financial information, assess your personal circumstances and prepare the advice. The analysis is focused on the specific question agreed at the initial consultation, not on a broader review of your full financial position unless that is within scope.
Present
We present the recommendation through the statement of advice, which documents the basis for every recommendation, the fees charged, and any conflicts of interest. We walk you through the advice clearly and answer questions before you decide whether to implement it.
Implement and Review:
Implementation of the advice is the client's decision and responsibility unless implementation support has been specifically included in the scope. If the one-off engagement reveals that ongoing advice would be appropriate, we explain what that would involve and what it would cost. There is no pressure to proceed beyond the original scope.
Next Steps
An initial consultation with Japhia takes approximately 30 minutes and is free of charge. We will clarify the scope of the advice, confirm what information will be needed, and explain the fee structure before any commitment is made.
Adviser Profile
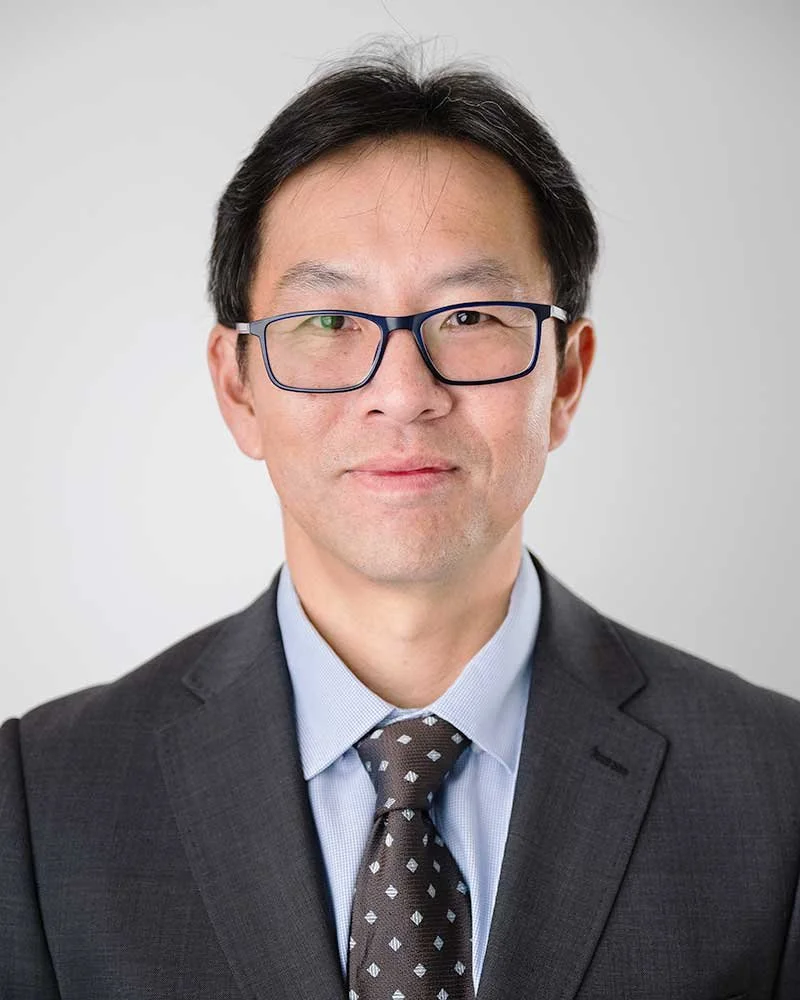
Meet Nicholas Wong – principal, japhia wealth advisory
Nicholas Wong is an authorised representative of Madison Financial Group (AFSL No. 246679). Nicholas has spent over 25 years working in the finance industry, with experience across financial planning, tax, superannuation and personal insurance. His goal is to provide well-considered, personalised wealth management advice that helps you grow, manage and protect your wealth over the long term.
Nicholas has extensive qualifications in finance and tax and has advised clients ranging from individuals to business owners. His clients value his ability to explain investment, superannuation, retirement planning and insurance options in simple terms and to give them a clear and actionable plan to achieve their financial goals. He is based at Level 24, 100 Miller Street, North Sydney.
Academic Qualifications:
Bachelor of Economics (University of Sydney)
Master of Applied Finance and Investments (FINSIA)
Master of Taxation (University of Sydney Faculty of Law)
Master of Financial Planning (Kaplan Professional)
Professional Qualifications:
Member of Chartered Accountants Australia and New Zealand
Member of the Chartered Institute of Securities and Investment (CISI)
Qualified Tax Relevant Provider as registered by Australian Securities and Investments Commission (ASIC)
What Sydney Clients Say About Japhia Wealth Advisory
“I would consider myself moderately sophisticated in money matters. Despite that, there will always be gaps in my knowledge and experience. A great financial advisor brings complimentary deep knowledge to enhance understanding and avoid pitfalls. Subtleties in tax and superannuation law can penalize an ill-considered investment or dramatically enhance a good choice. I have found Nick to be a careful and considered financial advisor. He has a wealth of knowledge regarding structures. His communication is first class. He works tirelessly behind the scenes to make things happen. Being time poor, I would have struggled to achieve the milestones we have reached in the time we have reached them.”
P SINGH
“I am an active equities fund manager with over 20 years experience dealing with financial planners. Nobody I have ever met comes close to Nick's skillset, expertise and temperament. Highly recommended.”
J BENDEICH
“I was directed to Nick through a trusted friend and from the first meeting felt completely confident that he would give me uncomplicated, evidence-based advice. Nick took the time to understand my goals, carefully reviewed my options to give me advice I can rely on.”
P WOODRUFF
“My experience with Nick has been outstanding. I’m not the most timely and compliant client but Nick is professional, very knowledgeable and delivers what he promises. Highly recommended.”
T THIRUCHELVAM
Common Questions About One-Off Financial Advice
-
One-off advice is a single, bounded engagement covering a specific question or area of the financial position. Ongoing advice involves a continuing relationship with regular reviews, access to advice between meetings, and adjustments to the financial plan as circumstances change. Both involve personal advice and a statement of advice. The difference is scope and duration, not the quality of the advice itself.
-
Yes. One-off financial advice from a licensed financial adviser is personal advice under the Corporations Act. It requires the adviser to understand your personal circumstances and financial situation before making any recommendation. It must be appropriate for your needs and documented in a statement of advice. It is not general advice, which does not take personal circumstances into account.
-
The free initial consultation takes approximately 30 minutes. The time required to prepare and deliver the advice depends on the complexity of the question and the financial position involved. A focused superannuation review typically takes one to two weeks from the initial consultation to delivery of the statement of advice. More complex engagements may take longer.
-
It depends on the question. For a superannuation review, bring the most recent fund statement. For a retirement income assessment, bring a summary of all assets and income sources. For an insurance review, bring current policy documents. For a second opinion engagement, bring the full statement of advice you have received. The more specific and complete the information, the more useful the one-off advice engagement will be.
-
Yes. Some clients who come for a one-off engagement decide they want ongoing advice once they have experienced the engagement. This is entirely possible and simply requires agreeing the scope and fee for an ongoing relationship. There is no additional set-up cost because the financial position has already been understood from the one-off engagement.
-
Item descriptionJaphia charges a one-off fee agreed upfront before any advice work begins. The fee depends on the complexity of the question and the financial position relevant to answering it. A focused superannuation or insurance review typically sits at the lower end of the fee scale. A retirement income assessment or investment strategy review involving more modelling and documentation typically costs more. The fee is disclosed and agreed before any commitment is made.
-
Item descriptionYes. Under Australian financial services law, a statement of advice (SOA) is required for any personal financial advice, including one-off advice. The SOA documents the recommendations made, the basis for each recommendation, the fees charged and any conflicts of interest. It is the formal record of the advice and should be retained.

Ready to Get One-Off Financial Advice in Sydney?
Your first conversation is free. We will clarify the scope of the advice you need, confirm the information required, and explain the fee before any commitment is made. No obligation. No sales pitch.
24/100 Miller Street North Sydney NSW 2060
+61 2 7202 8382
AFSL: 246679
GENERAL ADVICE WARNING: This information is of a general nature only and neither represents nor is intended to be specific advice on any particular matter. Madison Financial Group Pty Ltd strongly suggests that no person should act specifically on the basis of the information contained herein but should seek appropriate professional advice based upon their own personal circumstances.