
High Net Worth Financial Advice — Integrated Advice for a More Complex Financial Position
Japhia provides financial advice to older Australians covering retirement income planning, Age Pension optimisation, aged care financial planning, estate planning coordination and superannuation pension phase management. We are an authorised representative of Madison Financial Group (AFSL No. 246679), regulated by ASIC.
Financial advice for high net worth individuals is categorically different from standard financial planning. The decisions are more consequential, the structures more complex, and the cost of uncoordinated advice proportionally higher as the wealth base grows. A high net worth individual with significant wealth across superannuation, investment portfolios, property and business interests needs a financial adviser who sees the full picture and can coordinate every element rather than advising on each in isolation.
Japhia provides wealth management for high net worth individuals and families across Sydney. As your private wealth adviser, we build holistic, documented financial strategies that account for the full complexity of your position and review them as your circumstances, your assets and the legislation change. Our approach is entirely fee-for-service. There are no commissions from any product provider, which means every recommendation reflects your financial goals rather than what generates revenue for us.
What High Net Worth Financial Advice Actually Involves
High net worth financial advice is broader than investment management. It is the coordination of investment strategy, tax-effective ownership structures, superannuation, retirement planning, estate planning and succession planning into a single, integrated approach. The reason this coordination matters is that a decision made on one element without accounting for the others can create tax inefficiency, estate complications or unintended investment risk that a narrower engagement would never surface.
The distinction between private wealth management and product advice is important to understand before engaging any adviser. A product recommendation tells you what to buy. High net worth wealth management tells you how your financial position as a whole should be structured, what each element should be doing relative to the others, and how decisions across investments, tax, superannuation and estate planning interact. The output is a comprehensive, documented financial strategy, not a fund selection. For the broader framework this advice sits within, see our wealth management page.
Most high net worth clients arrive with what looks like a complete picture: an accountant managing their tax, a solicitor managing their legal structures, and possibly a broker managing their investments. What they typically lack is a financial adviser who sees how all three interact and can identify when a decision in one area creates a consequence in another. The absence of that coordination is one of the most consistent and expensive gaps in financial planning for high-net-worth individuals, and it is what high-net-worth financial advice directly addresses.
What an Integrated Financial Strategy Covers
An integrated financial strategy for a high net worth individual covers significantly more ground than a standard financial plan. It starts with a thorough understanding of the full financial position: income across all sources, assets across all structures, superannuation balances and investment options, property holdings, business interests and existing estate planning arrangements. Nothing is assessed in isolation because nothing operates in isolation.
Investment strategy is coordinated with the tax position rather than designed around returns alone. The tax treatment of different asset classes, the interaction between the investment portfolio and the superannuation balance, and the income requirements of a retirement that may last 25 to 30 years all affect how the investment strategy should be constructed.
Risk management is addressed across the full position rather than within a single portfolio. The question is not just what return the portfolio generates but whether the overall financial position, across all asset classes and structures, is exposed to the right level of risk given the client's financial objectives and risk tolerance.
Ownership structures are reviewed for tax efficiency and appropriateness to the client's current family situation, business interests and investable assets. Family trusts, company structures, superannuation and personal names each carry different tax treatment, different estate planning implications and different suitability at different stages of life. The right structure at 45 is not necessarily the right structure at 60, and restructuring at the wrong time carries its own costs.
An integrated strategy reviews this as part of the whole rather than addressing it only when a problem emerges. For high net worth clients who also need investment portfolio advice as a component of the broader strategy, our investment advice Sydney page covers that service in detail.
The Financial Decisions That Matter Most at This Wealth Level
Investment Portfolio Strategy and Management
A documented investment strategy at this wealth level covers more than asset allocation. It accounts for the tax treatment of different asset classes, the interaction between the investment portfolio and the superannuation balance, and the income requirements of a long retirement. We advise across a broad range of asset classes, including listed equities, managed funds, ETFs, private equity where appropriate, and direct investment.
At Japhia, we will:
assess your risk tolerance, time horizon and income requirements and build a tailored investment strategy around them;
recommend an appropriate mix of growth and defensive asset classes coordinated with your tax position and overall financial plan;
advise on investment strategies that reflect both short-term income needs and long-term capital growth objectives; and
review the portfolio regularly and recommend adjustments as markets, legislation or your circumstances evolve.
Tax-Effective Structures and Ownership
How assets are held affects how much return you keep. At a significant wealth level, the difference between appropriate and poor ownership structures compounds substantially over time. The right structure depends on income level, family situation, business interests and investment profile, and it should be reviewed as each of these changes.
At Japhia, we will:
assess how your assets are held across personal names, family trusts, companies and superannuation;
advise on restructuring decisions that reduce avoidable tax across the full financial position;
ensure tax efficiency is addressed as part of the integrated financial strategy rather than as a separate conversation; and
coordinate with your accountant and solicitor to ensure structures are implemented correctly and remain appropriate as legislation evolves.

Estate and Succession Planning
Estate planning is not only a legal exercise. The decisions around beneficiary nominations, superannuation death benefit directions, testamentary trust structures and how assets are positioned for intergenerational wealth transfer are financial planning decisions as much as legal ones. Transferring wealth to the next generation requires these elements to be coordinated. A lasting legacy is built through deliberate planning rather than default arrangements.
At Japhia, we will:
review beneficiary nominations across superannuation and investment accounts;
advise on superannuation death benefit directions and their tax implications for the estate;
coordinate with your solicitor on testamentary trusts, wills and powers of attorney; and
ensure the financial plan and the estate plan are consistent with each other and reflect the current asset structure.
Business Succession and Exit Planning
For high net worth clients whose wealth includes a business, succession and exit planning is one of the most significant financial decisions they will make. The tax treatment of a business sale, how proceeds are invested and structured, and how personal financial planning changes when business income ceases all require advice that should begin well before the intended exit date.
At Japhia, we will:
advise on the financial implications of a business sale or succession, including tax structure and proceeds investment;
coordinate personal financial planning around the transition from business income to investment and superannuation income;
model what retirement income looks like under different sale scenarios; and
work alongside your accountant and solicitor to ensure the exit is structured optimally across tax, legal and financial planning dimensions.

SMSF Strategy at Scale
A self-managed super fund is the right vehicle for some high net worth clients and not others, and that assessment should be revisited as wealth and life stage change. For clients with significant super balances approaching retirement, the questions extend beyond whether the SMSF is appropriate to whether the investment strategy within it, the pension transition timing and the compliance obligations are all being managed with appropriate rigour.
At Japhia, we will:
assess honestly whether the SMSF remains the right vehicle for your wealth level and life stage;
review the SMSF investment strategy against your financial goals and retirement timeline;
advise on the transition to pension phase and the tax implications of different timing decisions; and
coordinate with your SMSF accountant to ensure the fund remains compliant and the investment strategy is current.
The Investment Strategy Conversation High-Net-Worth Clients Need
For high-net-worth individuals, the investment strategy conversation is not primarily about fund selection or chasing returns. It is about how the overall investment position, across superannuation, direct holdings and managed investments, is structured to reflect the full financial picture.
High net worth individuals face specific investment challenges that standard portfolio advice does not address well. Concentration risk in a single business, property or stock position is common and consequential. The interaction between investment income, capital gains and the overall tax position affects which assets should be held in which structures. The question of how to preserve wealth through periods of market volatility, without making reactive decisions that lock in losses, is one that benefits from a documented investment philosophy established before the volatility arrives. Our article on how to navigate market volatility covers this in the context of managing an investment portfolio through uncertain market conditions.
Building wealth for the future requires an investment strategy that is coordinated with the broader financial plan rather than designed in isolation from it. The return on a portfolio matters. The tax treatment of that return matters as much. And the sequencing of drawdown in retirement, across superannuation and non-super assets, determines how much of that return the client actually keeps over the life of the strategy. These are the conversations that private wealth advisers need to have with high net worth clients that generic investment advice does not address.
The Cost of Uncoordinated Advice at a Higher Wealth Level
The most consistent financial risk facing high-net-worth individuals is not poor investment performance. It is uncoordinated advice. The accountant manages the tax position without knowing what the financial adviser is recommending for the investment portfolio. The estate plan was updated years ago and does not reflect the current asset structure. The SMSF investment strategy has not been reviewed since the market looked different. Each of these gaps is manageable in isolation. Together, across a complex financial position, they represent a significant and ongoing cost.
What coordination looks like in practice is one adviser who understands the full financial position and can see when a decision in one area creates a consequence in another. For high net worth wealth management to safeguard and optimise the client's position, the adviser needs to understand not just the individual components but how they interact. That is the standard that high net worth financial advice should be held to, and it is the standard Japhia applies.
For clients in the peak wealth-building stage of their career, our article on peak earners aged 45 to 55 covers the specific financial priorities and decisions that matter most at this stage, including where high net worth advice adds the most value.
Who WE HELP
Japhia provides high-net-worth financial advice to a specific set of clients across Sydney. What they have in common is that their financial position has grown complex enough that coordinated, integrated advice delivers materially more value than a series of unconnected product recommendations.
Business owners who have built substantial wealth inside a business and need advice on both the personal financial plan and the financial implications of transitioning out of it. Pre-retirees with significant superannuation, investment assets and property who have never had all three reviewed together against a clear retirement income objective. Executives with equity compensation, deferred remuneration or share options who need advice on the tax and investment implications of how that income is realised. Net worth individuals and families who want to build wealth for the future and preserve their wealth across generations through deliberate estate and succession planning. Clients who have received financial advice before but found it product-led rather than genuinely integrated across the full financial position.
If you are based on Sydney's North Shore, a financial adviser in North Sydney or a financial adviser in Chatswood who specialises in high net worth financial planning is accessible in person or via video call.
How We Work
Understand
We take the time to understand your complete financial position, including income, assets, liabilities, business interests, obligations and long-term financial goals. Nothing is assumed.
Analyse
We assess your investment portfolio, superannuation, tax position, ownership structures, estate planning arrangements and risk management position. We identify where coordination is missing and what a comprehensive integrated strategy should include.
Present
We walk you through our recommendations clearly. The strategies we propose, the structures we recommend, the reasoning behind each decision and the expected impact across your financial position. Nothing is presented without a clear explanation.
Implement and Review:
We put the strategy into action once you decide to proceed. With an ongoing engagement, we provide annual reviews, update you on legislative changes affecting your position, and remain your first point of contact when a financial decision arises between reviews.
An initial consultation with Japhia takes approximately 30 minutes and is free of charge. We will perform a preliminary assessment of your current financial position and discuss where the most meaningful opportunities lie. Appointments are available in person at our North Sydney office or online.
Adviser Profile
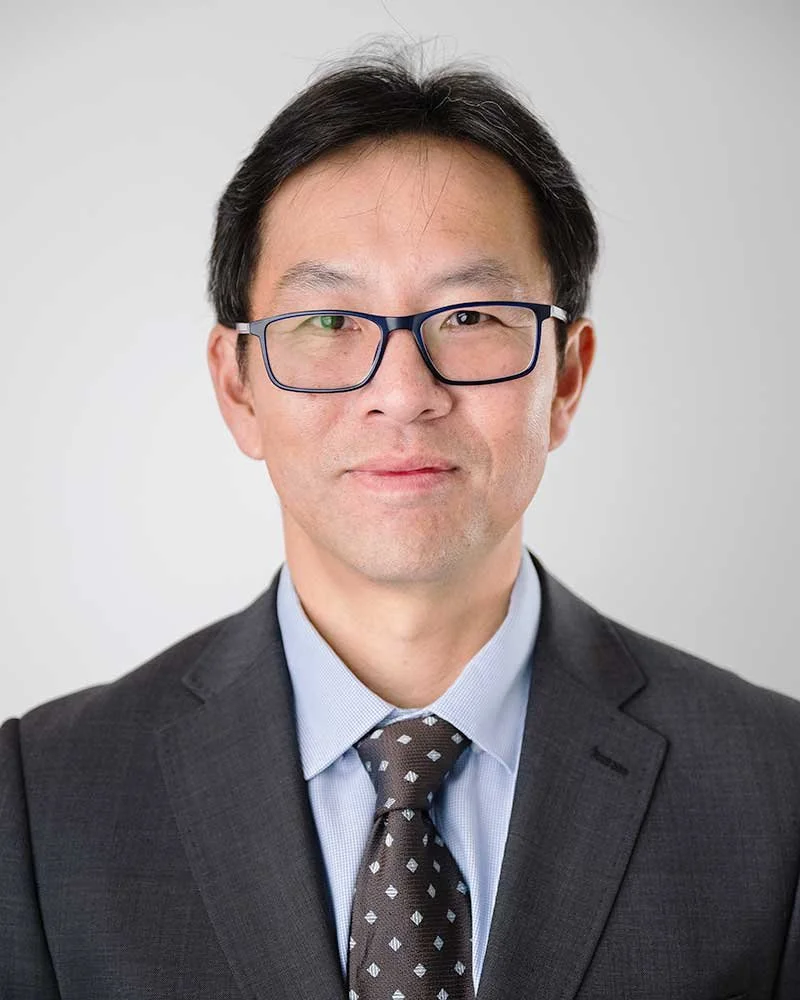
Meet Nicholas Wong – principal, japhia wealth advisory
Nicholas Wong is an authorised representative of Madison Financial Group (AFSL No. 246679). Nicholas has spent over 25 years working in the finance industry, with experience across financial planning, tax, superannuation and personal insurance. His goal is to provide well-considered, personalised wealth management advice that helps you grow, manage and protect your wealth over the long term.
Nicholas has extensive qualifications in finance and tax and has advised clients ranging from individuals to business owners. His clients value his ability to explain investment, superannuation, retirement planning and insurance options in simple terms and to give them a clear and actionable plan to achieve their financial goals. He is based at Level 24, 100 Miller Street, North Sydney.
Academic Qualifications:
Bachelor of Economics (University of Sydney)
Master of Applied Finance and Investments (FINSIA)
Master of Taxation (University of Sydney Faculty of Law)
Master of Financial Planning (Kaplan Professional)
Professional Qualifications:
Member of Chartered Accountants Australia and New Zealand
Member of the Chartered Institute of Securities and Investment (CISI)
Qualified Tax Relevant Provider as registered by Australian Securities and Investments Commission (ASIC)
Common Questions About High Net Worth Financial Advice
-
Standard financial advice typically addresses one or two aspects of a client's financial position, such as superannuation or insurance, with a relatively straightforward plan. High net worth financial advice addresses the full complexity of a significant financial position, including investment strategy across multiple asset classes, tax-effective ownership structures, estate and succession planning, business interests and superannuation at scale. The level of integration across each element is what distinguishes it.
-
There is no single threshold, but integrated high net worth financial advice delivers its clearest value when the financial position has grown complex enough that decisions in one area create meaningful consequences in others. This typically becomes apparent as business interests, superannuation, investment portfolios and property all accumulate alongside each other without a single adviser coordinating the full picture.
-
We work alongside your accountant and solicitor rather than replacing them. Your accountant manages tax compliance. Your solicitor manages legal structures. Our role is to ensure the financial strategy is consistent with both and to identify where a decision in one area creates implications in another that have not been addressed. We manage that coordination actively rather than leaving it to happen by default.
-
Japhia charges a transparent fee agreed upfront before any engagement begins. There are no commissions from fund managers, insurers or product providers. The fee depends on the complexity of the financial position and the scope of work required. We explain the fee clearly before any commitment is made.
-
At minimum, annually. With an ongoing high net worth advice engagement, we conduct a formal annual review, flag relevant legislative changes as they arise, and remain accessible between reviews when a financial decision comes up or circumstances change. For clients with complex positions, meaningful decisions arise between formal review dates regularly, and direct access to the adviser is part of the engagement.
-
Yes. SMSF advice is one component of the integrated financial strategy we build for high net worth clients. This includes assessing whether the SMSF remains the right structure at the client's current wealth level and life stage, reviewing the investment strategy within the fund, advising on the pension transition, and coordinating with the SMSF accountant on ongoing compliance. The SMSF is assessed in the context of the full financial position, not as a standalone product.
-
Item descriptionWe provide the financial planning dimension of estate planning, including beneficiary nominations, superannuation death benefit directions and the financial implications of different estate structures. The legal documentation is prepared by your solicitor. We coordinate directly with your solicitor to ensure the financial plan and the estate plan reflect each other.

Ready to Talk to a High Net Worth Financial Adviser in Sydney?
An initial consultation with Japhia takes approximately 30 minutes. We will assess your financial position and discuss where the most meaningful opportunities for improvement lie. No obligation. No sales pitch.
24/100 Miller Street North Sydney NSW 2060
+61 2 7202 8382
AFSL: 246679
GENERAL ADVICE WARNING: This information is of a general nature only and neither represents nor is intended to be specific advice on any particular matter. Madison Financial Group Pty Ltd strongly suggests that no person should act specifically on the basis of the information contained herein but should seek appropriate professional advice based upon their own personal circumstances.