
Financial Planning for High Income Earners — Sydney Professionals in the Accumulation Phase
A high income creates opportunity. Whether that opportunity is being captured effectively is a different question.
Japhia Wealth Advisory works with high income professionals across Sydney and the Lower North Shore who want a financial plan built around their actual position, not a generic framework applied to their income bracket.
Japhia Wealth Advisory is an authorised representative of Madison Financial Group Pty Ltd (AFSL No. 246679). Phone: +61 2 7202 8382.
Many high income professionals in Sydney are earning more than they ever have, building assets steadily, and yet have never had their financial position reviewed in any depth. The superannuation has grown, but the investment option was chosen years ago and has never been revisited. The portfolio outside super exists, but it accumulated without a strategy behind it. The income is strong, but the financial position as a whole has never been coordinated around a clear long-term goal.
This is not unusual. It is simply what tends to happen when career and family take priority, and financial planning keeps getting deferred to next year. At a high income level, however, the cost of that deferral — in tax paid, in contribution opportunities missed, in an investment structure that has never been reviewed — is significant.
Superannuation at a High Income Level
Superannuation is one of the most effective wealth-building tools available to high income earners, but it requires deliberate management to produce results that reflect its potential. Most high income professionals are receiving compulsory employer contributions into a fund that was chosen years ago, in an investment option that has never been reviewed. The gap between what is there and what could be there, given the income level and the years remaining to retirement, is often larger than clients expect when they actually look at it.
The contribution strategies that make sense at a high income level are different from those that apply at lower income levels. Salary sacrifice, personal deductible contributions, carry-forward concessional contributions, and the interaction between contributions and the Division 293 tax — these are decisions that depend on the overall income level, the existing contribution history, how close the client is to caps, and how superannuation fits into the broader financial position. We advise on contribution strategy and investment option selection as a central part of every engagement with high income earners, and for clients who hold or are considering a self-managed super fund, we assess whether that structure still fits their position and goals.
Building an Investment Strategy Outside Superannuation
Superannuation alone will not produce the retirement income most high income earners are working toward, particularly those who intend to stop work before the standard preservation age. Building a portfolio outside super requires deliberate decisions: what to hold, how to hold it, and how it fits alongside the super balance and the overall financial position.
For high income earners, ownership structure matters more than most people realise. Whether assets are held personally, jointly, or through another structure affects both the tax on investment returns and the overall position over time. Without a clear investment strategy, portfolios accumulate by default rather than by design — a parcel of shares here, a managed fund there, with no coherent rationale connecting any of it to a goal. We build investment strategies for high income earner clients that are structured around their income level, their timeline, and what they are actually trying to achieve.
Wealth Management Across the Full Picture
Wealth management at a high income level is about coordinating the full financial position — superannuation, investment portfolio, income, insurance and tax efficiency — so that each element is working toward the same objective rather than being managed as a series of separate decisions.
The professionals who get the most from financial planning at this income level tend to be those who have an ongoing relationship with an adviser who knows their position in depth, rather than seeking a periodic review when something goes wrong or a decision can no longer be deferred. A financial position built over years of strong earnings deserves ongoing management that reflects how circumstances evolve, how markets move, and how the long-term goal develops over time.
Retirement Planning for a High Income Earner
For most high income earners, the question is not whether there will be enough to retire on. The question is whether the transition from working income to retirement income has been structured in a way that maximises what is available and minimises the tax on it. The decisions made in the decade before retirement — whether super contributions have been maximised, how the investment portfolio is positioned as retirement approaches, what the drawdown strategy looks like — carry consequences that extend well beyond the transition itself.
We provide retirement planning advice that starts from the actual position: the actual balance, the actual assets, the actual income the client wants in retirement. Not a projection based on industry averages.
Protecting What Has Been Built
Income protection is frequently underinsured among high income earners. A policy taken out when income was lower and never reviewed since is common, and the gap between what the policy would pay and what the actual income now is can be significant. At a high income level, the financial consequence of an extended period unable to work is substantial. We review insurance as part of every engagement and assess whether the cover in place still reflects the client's current income and obligations.
Who We Work With
Our high income earner clients are typically professionals between 45 and 60 who are in the peak earning years of their career. They include corporate executives and senior managers across Sydney, legal and financial services practitioners, medical specialists who reached higher income later in their career and want to make the remaining accumulation years count, and professionals who have significant superannuation and investment assets that have never been structured as a coordinated financial plan.
What they have in common is that they have reached a point in their financial lives where the position deserves more intention than it has been getting, and where the decisions made over the next ten to fifteen years will have a lasting impact on what comes after work.
If you are in the peak earning years between 45 and 55, this is the window where financial planning decisions carry the most weight. The life cycle of financial planning explains how the key decisions shift across different stages of a career.
Adviser Profile
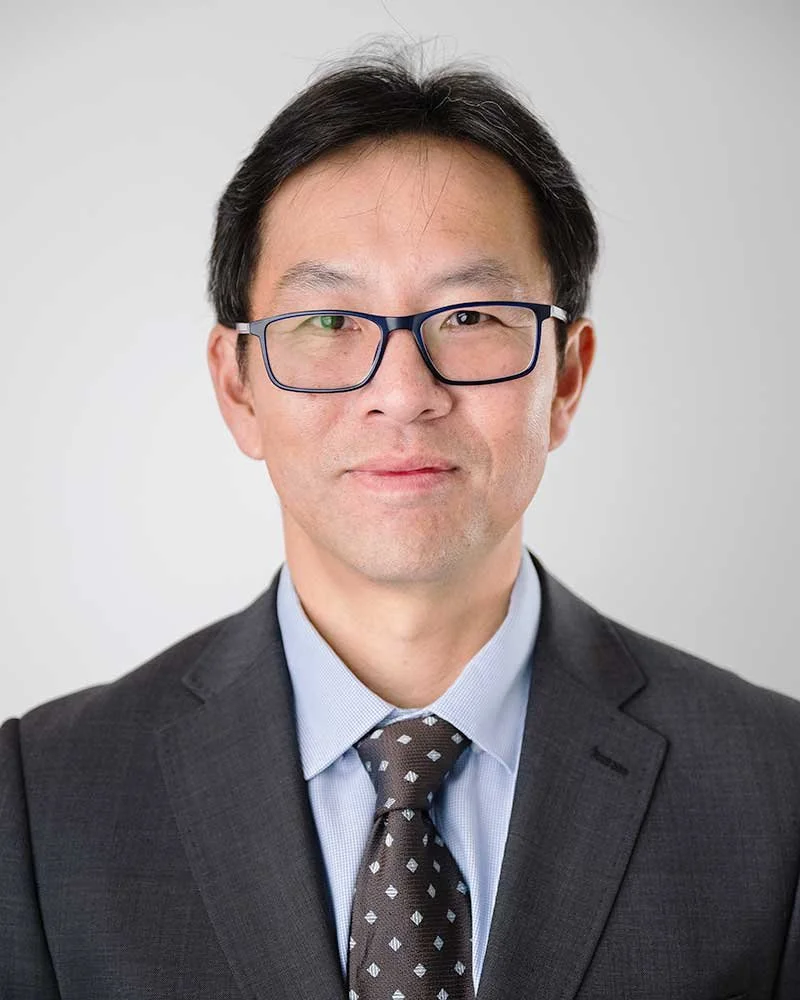
Meet Nicholas Wong — Financial Planner for High Income Earners
Nicholas Wong has spent more than 25 years working across finance, tax and financial planning. He advises professionals and established families across Sydney and the Lower North Shore on investment strategy, superannuation, retirement planning and personal insurance, with the tax implications of each recommendation considered as a matter of course.
Nicholas holds a Master of Taxation from the University of Sydney Faculty of Law alongside his financial planning qualifications. That combination is uncommon in financial planning and means clients receive advice that has been thought through across both dimensions from the outset.
He is an authorised representative of Madison Financial Group Pty Ltd (AFSL No. 246679) and is based at Level 24, 100 Miller Street, North Sydney.
Academic Qualifications:
Bachelor of Economics (University of Sydney)
Master of Applied Finance and Investments (FINSIA)
Master of Taxation (University of Sydney Faculty of Law)
Master of Financial Planning (Kaplan Professional)
Professional Qualifications:
Member of Chartered Accountants Australia and New Zealand
Member of the Chartered Institute of Securities and Investment (CISI)
Qualified Tax Relevant Provider as registered by Australian Securities and Investments Commission (ASIC)
Common Questions
-
We typically work with clients who have investable funds of $500,000 or above, or who are on a trajectory toward that level. This is not a fixed threshold, but it reflects the clients whose financial position benefits most from the kind of ongoing advice we provide.
-
The decisions at this income level carry more consequence, the tax implications are more significant, and the range of strategies available is broader. Advice that works well for someone earlier in their career — or at a lower income level — may not be the right approach for a high income earner in the accumulation phase. We start from where the client actually is, not from a template.
-
We work alongside your accountant rather than replacing them. Where our recommendations have tax implications, we document those clearly. For clients who want us to liaise directly with their accountant on a specific matter, we do that as part of the engagement.
-
Typically once or twice a year for a formal review, with contact between reviews as circumstances change or a specific decision comes up. The frequency reflects what is useful for the client's position, not a schedule applied to everyone.

Book a Discovery Session
A discovery session is a 30-minute conversation to discuss your current financial position and what you are looking to achieve. No advice is given in this session. Paperwork is completed beforehand so the time is spent on the conversation.
GENERAL ADVICE WARNING: This information is of a general nature only and neither represents nor is intended to be specific advice on any particular matter. Madison Financial Group Pty Ltd strongly suggests that no person should act specifically on the basis of the information contained herein but should seek appropriate professional advice based upon their own personal circumstances.