
Financial Adviser Cremorne: FINANCIAL Advice for those Who Have Built Something Worth Protecting
Japhia Wealth Advisory provides investment advice, superannuation planning, SMSF advice and wealth management to clients across Cremorne and the Lower North Shore. We are located nearby at Level 24, 100 Miller Street, North Sydney and we offer video call appointments for clients who prefer to meet from home. We are an authorised representative of Madison Financial Group (AFSL No. 246679), regulated by ASIC.
Cremorne has many established professionals and families who have spent 15 to 20 years building income, property equity and superannuation and are now in the phase where what they do with that position in the next 15 to 20 years matters as much as everything that came before. This is not a suburb of people starting out. It is a suburb where professionals and families are in the acceleration phase of their wealth creation - their careers are well advanced, promotions and mature business operations mean there is regular and increasing excess cashflow which allows them to invest and reduce debt. They have the financial resources, the question is whether those resources are being managed deliberately enough to produce the outcomes these professionals and families want.
Japhia provides financial advice to Cremorne professionals and families who are still building their wealth and want a coordinated strategy that works across every element of their financial position. We are a fee-for-service practice. The advice is based on what we believe is in the client's best interests given their financial circumstances.
What Changes When Wealth ACCELERATES
For most clients, their financial position at 45 looks nothing like it did at 30. At 30, it was income, rent or an early mortgage and a super balance that had been growing for a decade without much attention. By 45, it could be a bigger home loan balance alongside significant equity, superannuation across potentially multiple funds, an investment portfolio that may have accumulated through share purchases, managed funds or a spouse's assets without an investment strategy that balances risks and returns, and possibly a business interest or a partnership stake that sits alongside the personal financial position without ever having been properly coordinated with it.
At that point, financial complexity has outgrown whatever passive management was in place before. The superannuation default option that was set when the account was opened may not reflect the investment objectives of someone who is fifteen years from retirement rather than thirty. The insurance that was adequate when the mortgage was smaller, the income was lower and there were no dependents may no longer cover the household's actual obligations. And the investment portfolio may carry concentration risk, fee drag or a tax structure that is not optimal for the income level at which the client now operates.
This is the moment where a wealth management approach that coordinates every element, investment strategy, superannuation, tax structures, insurance and the interaction between the business and the personal position, delivers materially more than a series of individual product recommendations. For our Cremorne clients at this stage of life, the most valuable use of a financial planning engagement is a thorough review of what is there, what it is doing, and what a coordinated strategy looks like. Once there is an actionable plan, Japhia will help its clients with implementation. With an ongoing engagement, Japhia will also perform regular reviews to ensure the advice remains appropriate and its time-poor clients stays on track to achieve their long term financial goals.
Investment Strategy Beyond the Family Home
The family home in Cremorne has almost certainly grown significantly in value over the past fifteen to twenty years. For many clients in this suburb, this represents the majority of household net wealth. That is a good thing but it is not an investment strategy. A single, illiquid asset with no income yield and no alignment to specific financial goals is a starting point, not a plan.
Getting advice on building an investment portfolio alongside the family home, structured in a way that accounts for household income level, tax position, superannuation balance and investment time horizon is the conversation that turns a property-concentrated balance sheet into a coordinated approach to wealth accumulation. The decisions involved, which investment asset classes, which ownership structures, how the portfolio interacts with superannuation, and how the tax on investment returns is managed, require specific advice rather than a generic allocation.
For Cremorne clients who already hold some investment assets but have never had a documented investment strategy that reflects their risk appetite and target returns, a portfolio review is often the first useful step. Our article on how to navigate market volatility covers how a documented investment philosophy protects clients from making reactive decisions when markets become difficult, providing clarity when they most need it. For the broader framework that the investment strategy sits within, our investment advice Sydney page covers this in detail. For the broader framework of wealth management as a coordinated service, that page covers the full picture.
SMSF Advice for Cremorne Professionals
Self-managed super funds (SMSFs) come up regularly in conversations with Cremorne clients. The appeal is straightforward: direct control over investment decisions, the ability to hold assets that are not available in retail or industry funds, and a structure that can be tailored to specific estate planning objectives.
The suitability question is the one that matters more than the appeal. An SMSF suits some clients but it can be entirely inappropriate for others, and the difference depends on the super balance, the investment strategy, the willingness to manage trustee obligations and the costs relative to what an industry or retail fund would provide. For Cremorne clients with substantial super balances and specific investment objectives that cannot be achieved within a standard fund, an SMSF can be the right vehicle. For those whose super balance does not justify the fixed costs, or who want to hold investments that are available in a standard fund without the compliance burden, it is possibly not.
Japhia assesses SMSF suitability honestly. Where an SMSF is appropriate, we advise on establishment, investment strategy, the transition to pension phase and coordination with the SMSF accountant for set up and ongoing compliance. Where it is not, we say so directly and explain what a better-suited structure would look like. For details on how SMSF advice works in practice, see our SMSF advice Sydney page.
Who We Help in Cremorne
Corporate executives and professionals - successful people who have the capacity to accelerate their wealth accumulation but are so busy generating higher income they have neglected to put in place a documented long term financial plan or have no time to monitor their strategy regularly.
Business owners who need personal financial planning coordinated with their business structure and interests.
Pre-retirees who are still fifteen years from stopping work but want to start directing their investments deliberately.
Families managing significant household income alongside a Cremorne mortgage and competing financial priorities who want to deploy their earnings under a clear sequence rather than default management.
Japhia works with these clients across Cremorne and the surrounding suburbs who are managing a financial position that has grown complex and they want it addressed properly rather than managed around the edges.
For clients who want to explore the broader North Shore adviser network, we are also the financial adviser North Sydney closest to Cremorne and serve clients across the Northern Beaches from financial adviser Northern Beaches to the Lower North Shore from the same North Sydney office.
Our article on peak earners aged 45 to 55 is worth reading for Cremorne clients who identify with this stage of life and want to understand what financial decisions carry the most weight in this window.
What Sydney Clients Say About Japhia Wealth Advisory
“I would consider myself moderately sophisticated in money matters. Despite that, there will always be gaps in my knowledge and experience. A great financial advisor brings complimentary deep knowledge to enhance understanding and avoid pitfalls. Subtleties in tax and superannuation law can penalize an ill-considered investment or dramatically enhance a good choice. I have found Nick to be a careful and considered financial advisor. He has a wealth of knowledge regarding structures. His communication is first class. He works tirelessly behind the scenes to make things happen. Being time poor, I would have struggled to achieve the milestones we have reached in the time we have reached them.”
P SINGH
“I am an active equities fund manager with over 20 years experience dealing with financial planners. Nobody I have ever met comes close to Nick's skillset, expertise and temperament. Highly recommended.”
J BENDEICH
“I was directed to Nick through a trusted friend and from the first meeting felt completely confident that he would give me uncomplicated, evidence-based advice. Nick took the time to understand my goals, carefully reviewed my options to give me advice I can rely on.”
P WOODRUFF
“My experience with Nick has been outstanding. I’m not the most timely and compliant client but Nick is professional, very knowledgeable and delivers what he promises. Highly recommended.”
T THIRUCHELVAM
Adviser Profile
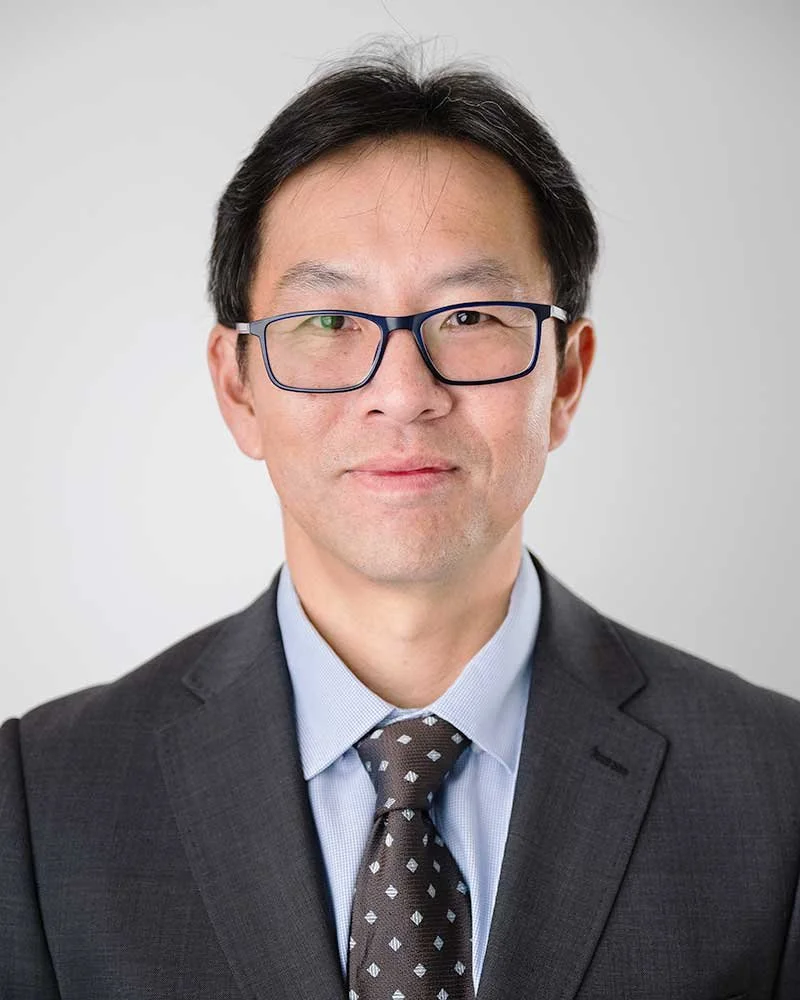
Meet Nicholas Wong – principal, japhia wealth advisory
Nicholas Wong is an authorised representative of Madison Financial Group (AFSL No. 246679). Nicholas has spent over 25 years working in the finance industry, with experience across financial planning, tax, superannuation and personal insurance. His goal is to provide well-considered, personalised wealth management advice that helps you grow, manage and protect your wealth over the long term.
Nicholas has extensive qualifications in finance and tax and has advised clients ranging from individuals to business owners. His clients value his ability to explain investment, superannuation, retirement planning and insurance options in simple terms and to give them a clear and actionable plan to achieve their financial goals. He is based at Level 24, 100 Miller Street, North Sydney.
Academic Qualifications:
Bachelor of Economics (University of Sydney)
Master of Applied Finance and Investments (FINSIA)
Master of Taxation (University of Sydney Faculty of Law)
Master of Financial Planning (Kaplan Professional)
Professional Qualifications:
Member of Chartered Accountants Australia and New Zealand
Member of the Chartered Institute of Securities and Investment (CISI)
Qualified Tax Relevant Provider as registered by Australian Securities and Investments Commission (ASIC)
Common Questions from Cremorne Clients
-
Your accountant manages your tax compliance, business obligations and financial history. A financial adviser manages your financial future, investment strategy, superannuation, SMSF advice, personal insurance such as income protection and how each of these elements interacts with the others. The roles address different things and are most effective when they are coordinated. We work alongside your accountant as a standard part of how we operate.
-
No. Concentrated property wealth is a starting point, not a plan. The equity is illiquid, produces no income, and carries no inherent connection to a financial goal. What to do with that equity, including whether to hold, leverage, or diversify into investment assets, depends on your income, your superannuation balance, your tax position and your investment time horizon. We assess this as part of a complete financial planning engagement rather than providing a generic answer.
-
It depends on your superannuation balance, the investment strategy you want to pursue, and how comfortable you are managing trustee obligations. An SMSF can be appropriate for our Cremorne clients with a significant super balance and specific investment objectives that cannot be achieved in a retail or industry fund. It is not appropriate for everyone who can afford one. We assess this honestly rather than recommending it by default.
-
Yes, and treating them as a connected strategy rather than separate decisions is the most useful approach. How the investment portfolio and the superannuation balance interact, how the tax treatment of each affects the overall position, and how they should be managed over time are conversations that produce better outcomes when addressed together.
-
Yes, our first catch up is free and will take approximately 30 minutes. We want to find out more about you and what financial advice you need. We will explain our services and how we can add value. The conversation will focus on identifying your high priority items and the scope of work required to address those. We can provide an indication of cost but there is no commitment until you decide to proceed.

Ready to Talk to a Financial Adviser in Cremorne?
Your first conversation with Japhia costs nothing. We will take the time to understand your financial position and explain what a coordinated financial strategy built around it would look like. No obligation. No sales pitch.
24/100 Miller Street North Sydney NSW 2060
+61 2 7202 8382
AFSL: 246679
GENERAL ADVICE WARNING: This information is of a general nature only and neither represents nor is intended to be specific advice on any particular matter. Madison Financial Group Pty Ltd strongly suggests that no person should act specifically on the basis of the information contained herein but should seek appropriate professional advice based upon their own personal circumstances.